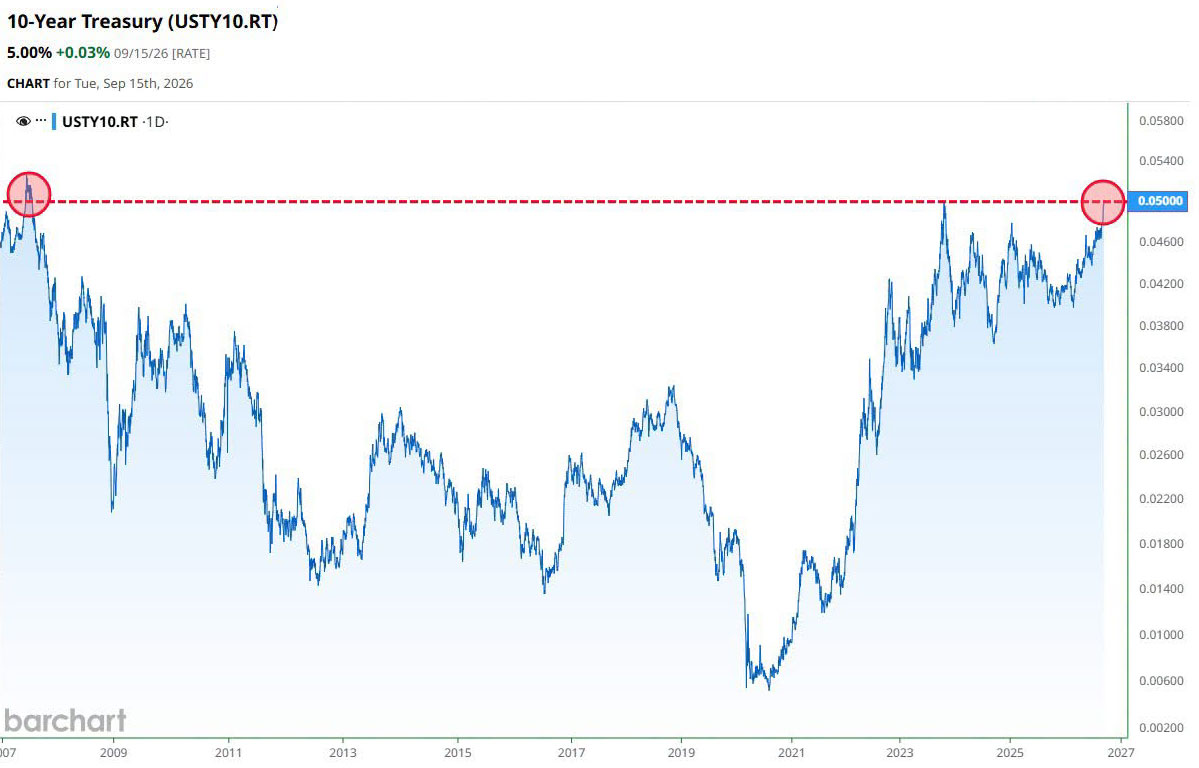
With mortgage rates at around 7%, anyone who got used to the near 3% home loans of 2020/21 will think they're high.
But a look back in time proves they are actually closer to normal today!
From the mid-1990's through 2000, annual averages ran about 7% to 8%. The long-run average since the 1970's is roughly 7.5–7.8%. Rates then spent most of 2009–2019 in the 3's and 4's, and hit an all-time low near 3% in 2021. The jump since 2022 reversed that unusual stretch.
So 7% is not a new world. It is a very normal one.
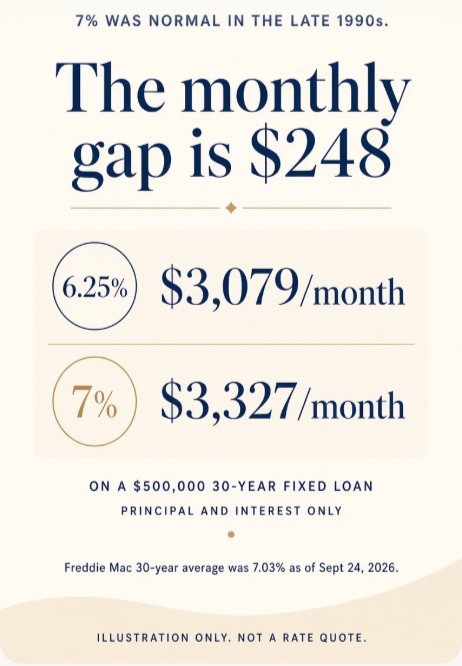
Here's the practical difference on a $500,000 conventional 30-year fixed loan, principal and interest only:
At 6.25%: about $3,079 per month
At 7%: about $3,327 per month
Gap: about $248 extra per month
Remember also that most buyers don't keep their original loan for its entire life. Refinancing when it's beneficial to do so may reverse higher monthly payments.
Should you just wait? Home prices, available inventory and your own timeline actually matter as much as the rate, often even more so.
If you can live with the extra monthly payment today, with the option to refinance later, that's frequently a stronger plan than waiting for the perfect number that may, or may never, arrive, and possibly after prices have already moved out of your favor.
Give us a call to informally discuss your best strategy - 435-327-2090.